
Below you can find the latest updates to our learning resources. We recommend checking this section regularly to stay informed of any changes. Updates may arise from:
• Revisions to the exam syllabus
• Amendments to the relevant CII study texts that directly impact our materials
• Corrections to typographical errors
• Adjustments addressing more complex issues
By reviewing these updates, you can ensure your study materials remain accurate and aligned with current requirements. Simply click onto the Study Material required and any updates will display below.
Please note: The Categories for the filters will only appear if there are posts within that category. If a category doesn’t have any posts within it, it wont display to users.
Keeping your study materials up to date is essential for exam success.
To ensure you are working with the most accurate resources, we recommend checking this page regularly. Here you will find updates that directly affect your study materials, helping you stay aligned with the latest requirements
Updates to your study materials are published directly on the CII website at www.cii.co.uk. To locate them, select your exam unit and look for the “Unit Updates” section displayed in the right‑hand column. We recommend reviewing both the “Learning Solutions Update” and “Qualification Update” headings to ensure you are working with the most current information.
Self-test questions – answer 2.1
The third bullet point in the ‘Jessica dates and basis of amounts‘ table should ready 2028 rather than 2027.
The correct sentence therefore is: 31st January 2028. This will be a balancing payment for 2026/27 for the difference between the tax due for 2026/27 and the £4,000 paid so far under the payments on account. Plus there will be a first payment on account for the tax year 2027/28.
Our Autumn 2026 budget summary can be found by clicking the More Info button.
Question 39: Angus, aged 43, has lived in Edinburgh all his life. He has been assessed as needing personal care due to immobility issues. To what might he be entitled?
The correct answer should be option B: Free personal care up to the value of £260.30 per week. The figure of £254.60 was previously stated in error.
Chapter 9 / page 348 / example 9.3
Example 9.3 was incorrect in the study guide. It has been re=written as per the attached.
Activity 7.3
To avoid ambiguity, the first question in activity 7.3 has been amended. The rationale remains the same.
Original question: Calculate the value of the gifts that should go into the lifetime transfer bucket. (6 marks)
Revised question: Calculate the value of the gifts made in his lifetime (6 marks)
Page: 140
Chapter: 3
Section: 3.3.3b – Surplus Treaty or Surplus Line Treaty
Update Summary
The previous example referred to a single claim of £30 million arising from a £15 million risk. This was not technically correct, as a claim payment cannot exceed the insured value of the underlying risk. To address this, the example has been revised to show two separate claims of £15 million each, resulting in a combined claims total of £30 million while remaining consistent with the original £15 million risk exposure.
Revised Example
If two separate claims of £15 million are made, each claim is shared in line with the original risk split of one retained line and two surplus lines:
Across both claims, the total paid would be:
As with other proportional reinsurance, claims are shared in the same proportions as the original risk and premium.
Chapter 1.2.2 – In Summary table
The FCA does not regulate the Bank of England as previously stated.
The FCA regulate recognised investment exchanges. This regulatory body can impose sanctions and fines if necessary.
Chapter 1.3 / page 24
The correct date which the UK’s transition period from the EU ended was 31st December 2020 not 21st December as previously stated.
Chapter 1.3.2 / page 26
FSMA stands for Financial Services and Markets Act rather than Financial Services and Marketing Act as previously stated.
Chapter 1.4.5 / page 32
The last paragraph in this section has been reworded to make it clearer. It now reads:
As at May 2024, interest rates stood at 5.25%. While it was expected that these rates would eventually fall, there was no certainty about when this would happen. By February 2026, interest rates had gradually fallen to 3.75%, while inflation stood at 3% which was above the Bank of England’s 2% target. Interest rates have historically risen and fallen in response to changing economic conditions, and are likely to continue to fluctuate in the future.
Chapter 5B.1.2 / page 268
Example 5.8 regarding Capri Limited was incorrect. This example has therefore been re-written as follows:
| Example 5.8 Under the FCA’s MIFIDPRU rules, what is the primary purpose of requiring investment firms to hold adequate own funds? A. To maximise shareholder returns. B. To ensure firms have sufficient financial resources to absorb losses and protect clients. C. To guarantee all client investments will make a profit. D. To reduce the amount of tax paid by the firm. B is correct. Under the MIFIDPRU prudential regime, investment firms must maintain adequate own funds to help ensure their financial resilience. This enables firms to absorb losses, continue operating during periods of financial stress, and reduce the risk of harm to clients and markets. |
Chapter 5A.3.3b: Civil and criminal courts enforcement / page 331.
The maximum prison term for making misleading statements or misleading conduct should be 10 years, not 7 years.
Section 1.4.4 – SDLT
A section has been added to this chapter regarding the SDLT paid by companies:
SDLT applies to both individuals and non-natural entities including companies.
In most cases, the higher rates of SDLT (as shown below) apply to companies under the following circumstances:
The SDLT rates applicable to companies, based on the value of the property, are as follows:
| Purchase Price /Lease Premium / Transfer Value | Resident Corporate Bodies | Non-Resident Corporate Bodies |
| Up to £125,000 | 5% | 7% |
| £125,001 to £250,000 | 7% | 9% |
| £250,001 to £925,000 | 10% | 12% |
| £925,001 to £1.5 million | 15% | 17% |
| Over £1.5 million | 17% | 19% |
Chapter 1.2.7
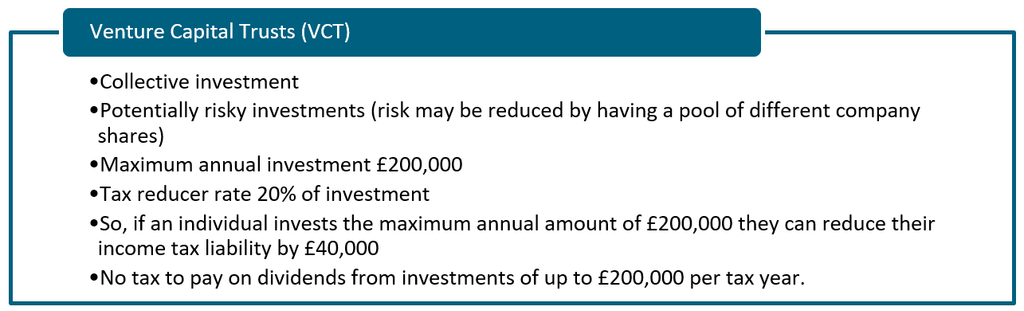
In the table labelled Venture Capital Trust, we incorrectly stated that the tax reducer rate was 30%. The correct figure is 20%. This has now been corrected as follows:
Section 1.2.4 – Charity contributions made via Gift Aid
The study guide originally stated the following: The charity must be established in the UK, or in another EU member state, or in Norway or Iceland. The charity itself can only recover the 20% basic rate amount, regardless of the tax position of the donor
Since Brexit, this is no longer correct. We have changed the study guide to read the following:
To claim Gift Aid, the charity must be recognised by HMRC for tax purposes. The charity can reclaim the basic-rate tax element of a donation, currently worth 25p for every £1 donated. Any additional tax relief due to higher-rate or additional-rate taxpayers must be claimed by the donor and cannot be reclaimed by the charity
Chapter 3.2.2 / page 53
The Benefits for short and long-term sickness summary table has been corrected to the attached.
Question 74: Stefan is purchasing a residential property to add to his property portfolio. The purchase price is £150,000 and he will achieve rental income of £560 per month. He should be aware that…
The SDLT calculation in the rationale was incorrect. This did not affect the correct answer to the question, but to clarify the correct SDLT for Stefan would be:
First SDLT £125,000 at 5%: £125,000 × 5% = £6,250
Remaining SDLT £25,000 at 7%: £25,000 × 7% = £1,750
Total SDLT payable: £6,250 + £1,750 = £8,000
Q190 has been rephrased as follows: Kathy, a higher rate taxpayer is completing her tax return online. All her earned income is taxed by PAYE and she has also received some income distributions from her range of OEICs. Her UK equity fund paid her distributions of £5,750 and her high-yield corporate bond fund distributions totalled £1,050. How much income tax is payable to HMRC on these distributions assuming these are all of Kathy’s savings and investments?
Example 1.23
There was a type in example 1.23 however the totals were all correct. The correct wording should be:
1.23
Charles and Robert have exchanged properties. Neither are first-time buyers.
They are trying to save on costs such as agent fees and SDLT.
Robert’s property, which Charles bought, was worth £550,000 and Charles’ property, which Robert bought, was worth £552,000. How much SDLT will they save?
Charles £0 – £125,000 x 0% = £0
£125,001 – £250,000 x 2% = £2,500
£250,001 – £550,000 x 5% = £15,000
Total Stamp Duty Land Tax = £17,500
Robert £0 – £125,000 x 0% = £0
£125,001 – £250,000 x 2% = £2,500
£250,001 – £552,000 x 5% = £15,100
Total Stamp Duty Land Tax = £17,600
Overall total: £17,500 + £17,600 = £35,100
There will be no SDLT saving, as stamp duties cannot be avoided by exchanging properties. It will still be charged on the current market value of each property.
End of chapter question 19 – Peter, a higher rate taxpayer, has £90,000 of savings in his only building society account. Karen, an additional rate taxpayer, has £101,000 in her only bank deposit account. Both accounts provide the same interest rate. In comparing the two accounts you would note…
Answers C and D were both marked as correct in error. The only correct answer is D.
D. Karen’s account is less likely to provide voting rights.
Question 1
The new FSCS limit is £120,000 rather than £85,000.
We have therefore amended answer B to £245,000 which is the correct answer (answer C was previously highlighted as correct.
The revised rationale is:
The FSCS covers 100% of a deposit where the provider has become insolvent per person per marketing group, capped at £120,000.
Therefore, Paul and Alex’s joint account of £150,000 is entirely covered since they each would be protected for up to £120,000 on the accounts with Bank X. The £45,000 not used up by the joint account can be used by Paul for his sole account. In addition, Alex would have up to £120,000 protection with Bank Z so his sole account of £50,000 is covered in its entirety. So £75,000 +£75,000 + £45,000 + £50,000 = £245,000.
Question 176: Roger and Chastity were married and both were UK residents. Roger was of UK domicile but Chastity is of Belgium domicile. When Roger died earlier this year, his £1,050,000 estate, including the mortgage-free family home, was inherited by Chastity. How much inheritance tax, if any, was due?
This question has been re-written to reflect the new residency rules. The re-worded question now reads: Roger and Chastity were married. Roger was a UK long term resident but Chastity was from Belgium and was not a UK long term resident. When Roger died earlier this year, his £1,050,000 estate, including the mortgage-free family home, was inherited by Chastity. How much inheritance tax, if any, was due?
Question 35: Brian and Rhianna are married and have one daughter, Heather. Brian is a UK long term resident and Rhianna a Brazilian resident and not UK long term resident. Brian has died, leaving an estate of £850,000, including the mortgage-free family home valued at £600,000. What inheritance tax (IHT) liability will there be on his death if everything passes to Rhianna?
The correct answer is C – £80,000
Clarification: the £175,000 Residence Nil‑Rate Band (RNRB)is only applicable to Brian’s direct descendants (children / grandchildren) therefore Rhianna would not be able to use this even though the entire estate has been passed to her. We had previously calculated the answer with Rhianna being eligible to use this benefit which was incorrect.
The question has been amended to state that Brian and Rhianna had a daughter to avoid any further confusion.
The correct answer therefore is £850,000 – £325,000 NRB – £325,000 (for non-UK LTR spouse) = £200,000 x 40% = £80,000 (answer C).
Question 124: Chris and Jessica invested £20,000 into a joint onshore life assurance bond just over 8 years ago. They are considering surrendering the bond for £28,000 having taken no withdrawals. If Chris is a higher rate taxpayer and Jessica a basic rate taxpayer, how will any gain be assessed for income tax purposes?
The question previously stated that Chris and Jessica both invested £20,000 which would have meant that there was no gain to be assessed (£20,000 + £20,000 – £28,000 = -£12,000). Chris and Jessica actually invested £20,000 between them so there is a gain of £28,000 – £20,000 = £8,000.
Chapter 2.2.3: Class 1 Contributions – employers
The table showing the rates of secondary Class 1 NICs as shown in the R03 tax tables were incorrect. The correct rates are attached.
Answer C was marked as correct in error.
The correct answer should have been D. repayment of any excessive pension contributions made.
Question 41
Question text: Jeff, Simon and Marty have the following DC pension schemes respectively:
£44,000 section 32 buyout bond with guaranteed minimum pension
Which of the following statements are TRUE in relation to transferring these benefits?
£32,000 retirement annuity contract with a guaranteed annuity rate
£38,000 personal pension plan with protected tax free cash
Answers B and C were both marked as correct however the correct answers are C and D:
C: Jeff and Marty require independent advice prior to transfer.
D: All three members have protected / guaranteed benefits within their schemes.
Question 10
Question text: Naz has a personal pension of £800,000, a section 32 guaranteed minimum policy of £220,000 and an retirement annuity contract of £100,000. How much pension commencement lump sum (PCLS) could Naz take in the current tax year?
Answer D was incorrectly written as £22,5000. It should have been £225,000.
Q39 – Carol partially retired in July 2025, crystallising some of her defined contribution pension benefits into flexi-access drawdown from which she has been making withdrawals. Carol has been contributing £2,500 monthly to a personal pension plan for the last fifteen years. She now wishes to make an additional £15,000 single gross premium into this plan. What rules apply to her use of carry forward of the annual allowance (AA) and money purchase annual allowance (MPAA)?
The question has been modified to clarify exactly what is required.
Answer A is now correct: Carry forward in relation to both the AA and MPAA cannot be used by Carol.
