Material Updates

Material Updates

Are your CII Study Materials up to date?

Below you can find the latest updates to our learning resources. We recommend checking this section regularly to stay informed of any changes. Updates may arise from:


• Revisions to the exam syllabus
• Amendments to the relevant CII study texts that directly impact our materials
• Corrections to typographical errors
• Adjustments addressing more complex issues


By reviewing these updates, you can ensure your study materials remain accurate and aligned with current requirements. Simply click onto the Study Material required and any updates will display below.

Please note: The Categories for the filters will only appear if there are posts within that category. If a category doesn’t have any posts within it, it wont display to users.

Study Material Category Filter 26-27
Date Updated: August 17, 2026

Self-test questions – answer 2.1

The third bullet point in the ‘Jessica dates and basis of amounts‘ table should ready 2028 rather than 2027.

The correct sentence therefore is: 31st January 2028. This will be a balancing payment for 2026/27 for the difference between the tax due for 2026/27 and the £4,000 paid so far under the payments on account. Plus there will be a first payment on account for the tax year 2027/28.

Date Updated: October 8, 2026

Question 39: Angus, aged 43, has lived in Edinburgh all his life. He has been assessed as needing personal care due to immobility issues. To what might he be entitled?

The correct answer should be option B: Free personal care up to the value of £260.30 per week. The figure of £254.60 was previously stated in error.

Date Updated: October 26, 2026

Chapter 9 / page 348 / example 9.3

Example 9.3 was incorrect in the study guide. It has been re=written as per the attached.

Date Updated: August 6, 2026

Activity 7.3

To avoid ambiguity, the first question in activity 7.3 has been amended. The rationale remains the same.

Original question: Calculate the value of the gifts that should go into the lifetime transfer bucket. (6 marks)

Revised question: Calculate the value of the gifts made in his lifetime (6 marks)

Date Updated: October 27, 2026

The pass mark published in the study guide was incorrect. The correct pass mark is 70%, not 65%.

Date Updated: August 11, 2026

Page: 140
Chapter: 3
Section: 3.3.3b – Surplus Treaty or Surplus Line Treaty

Update Summary
The previous example referred to a single claim of £30 million arising from a £15 million risk. This was not technically correct, as a claim payment cannot exceed the insured value of the underlying risk. To address this, the example has been revised to show two separate claims of £15 million each, resulting in a combined claims total of £30 million while remaining consistent with the original £15 million risk exposure.

Revised Example

If two separate claims of £15 million are made, each claim is shared in line with the original risk split of one retained line and two surplus lines:

  • Insurer (1 retained line): £5 million
  • Surplus treaty (2 surplus lines of £5 million each): £10 million

Across both claims, the total paid would be:

  • Insurer: £10 million
  • Surplus treaty: £20 million (representing two surplus lines of £10 million each across both claims)

As with other proportional reinsurance, claims are shared in the same proportions as the original risk and premium.

Date Updated: July 17, 2026

Chapter 1.2.2 – In Summary table

The FCA does not regulate the Bank of England as previously stated.

The FCA regulate recognised investment exchanges. This regulatory body can impose sanctions and fines if necessary.

Date Updated: September 21, 2026

Chapter 1.3 / page 24

The correct date which the UK’s transition period from the EU ended was 31st December 2020 not 21st December as previously stated.

Date Updated: September 21, 2026

Chapter 1.3.2 / page 26

FSMA stands for Financial Services and Markets Act rather than Financial Services and Marketing Act as previously stated.

Date Updated: September 21, 2026

Chapter 1.4.5 / page 32

The last paragraph in this section has been reworded to make it clearer. It now reads:

As at May 2024, interest rates stood at 5.25%. While it was expected that these rates would eventually fall, there was no certainty about when this would happen. By February 2026, interest rates had gradually fallen to 3.75%, while inflation stood at 3% which was above the Bank of England’s 2% target. Interest rates have historically risen and fallen in response to changing economic conditions, and are likely to continue to fluctuate in the future.

Date Updated: September 28, 2026

Chapter 5B.1.2 / page 268

Example 5.8 regarding Capri Limited was incorrect. This example has therefore been re-written as follows:

Example 5.8

Under the FCA’s MIFIDPRU rules, what is the primary purpose of requiring investment firms to hold adequate own funds?

A. To maximise shareholder returns.
B. To ensure firms have sufficient financial resources to absorb losses and protect clients.
C. To guarantee all client investments will make a profit.
D. To reduce the amount of tax paid by the firm.

B is correct. Under the MIFIDPRU prudential regime, investment firms must maintain adequate own funds to help ensure their financial resilience. This enables firms to absorb losses, continue operating during periods of financial stress, and reduce the risk of harm to clients and markets.
Date Updated: September 7, 2026

Section 1.4.4 – SDLT

A section has been added to this chapter regarding the SDLT paid by companies:

SDLT applies to both individuals and non-natural entities including companies.

In most cases, the higher rates of SDLT (as shown below) apply to companies under the following circumstances:

  • When the value of the property is above £40,000.
  • When the interest accrued is not subject to a lease with more than 21 years remaining.

The SDLT rates applicable to companies, based on the value of the property, are as follows:

Purchase Price /Lease Premium / Transfer ValueResident Corporate BodiesNon-Resident Corporate Bodies
Up to £125,0005%7%
£125,001 to £250,0007%9%
£250,001 to £925,00010%12%
£925,001 to £1.5 million15%17%
Over £1.5 million17%19%
Date Updated: October 22, 2026

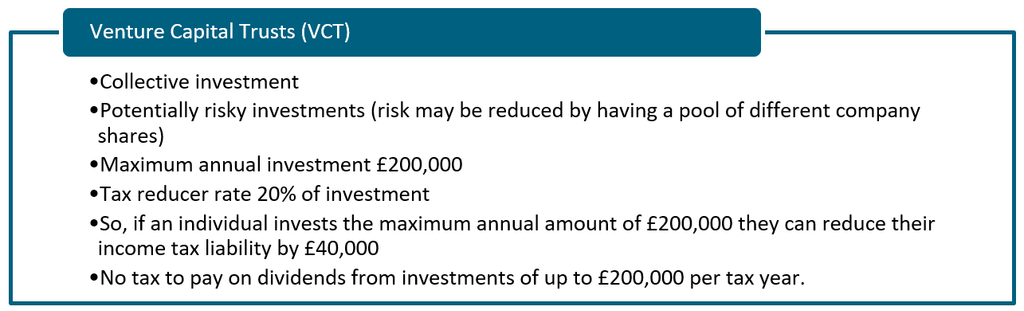
Chapter 1.2.7

In the table labelled Venture Capital Trust, we incorrectly stated that the tax reducer rate was 30%. The correct figure is 20%. This has now been corrected as follows:

Date Updated: October 22, 2026

Section 1.2.4 – Charity contributions made via Gift Aid

The study guide originally stated the following: The charity must be established in the UK, or in another EU member state, or in Norway or Iceland. The charity itself can only recover the 20% basic rate amount, regardless of the tax position of the donor

Since Brexit, this is no longer correct. We have changed the study guide to read the following:

To claim Gift Aid, the charity must be recognised by HMRC for tax purposes. The charity can reclaim the basic-rate tax element of a donation, currently worth 25p for every £1 donated. Any additional tax relief due to higher-rate or additional-rate taxpayers must be claimed by the donor and cannot be reclaimed by the charity

Date Updated: September 21, 2026

Chapter 3.2.2 / page 53

The Benefits for short and long-term sickness summary table has been corrected to the attached.

Date Updated: October 22, 2026

Chapter 3.2.4 / page 58

The Benefits relating to mortgages or rental costs summary table has been corrected to the attached.

2025-2026 Exam Updates

Study Material Category Filter 25-26
Date Updated: September 21, 2026
Date Updated: October 22, 2026

Keeping your study materials up to date is essential for exam success.

To ensure you are working with the most accurate resources, we recommend checking this page regularly. Here you will find updates that directly affect your study materials, helping you stay aligned with the latest requirements

Updates to your study materials are published directly on the CII website at www.cii.co.uk. To locate them, select your exam unit and look for the “Unit Updates” section displayed in the right‑hand column. We recommend reviewing both the “Learning Solutions Update” and “Qualification Update” headings to ensure you are working with the most current information.

SIGN UP TO OUR MAILING LIST